The Gucci Beauty Handoff | Coty’s Distressed Exit & L’Oréal’s License Consolidation
Coty agreed to return the Gucci Beauty license to Kering roughly a year ahead of schedule for about $400 million. The handoff looks like a small, technical license reversion. It is better understood as a $400 million courier fee paid to accelerate the consolidation of luxury beauty into one balance sheet — and as a clean illustration of how a maison’s scent has quietly become a capital-markets asset.
Read as a beauty story, it is a distressed licensor raising cash. Read as a capital-markets story — which is how it should be read — it is the second leg of a transaction we already covered: the deliberate, paid-for delivery of one of luxury’s most valuable scent franchises into L’Oréal’s 50-year vault. Kering does not want the license. It is the courier.
#LuxuryBeauty, #Gucci, #Coty, #Kering, #LOreal, #BrandLicensing, #FragranceMarket, #LuxuryMA, #Financialization, #RoyaltyStreams, #BusinessOfLuxury, #CapitalInsights, #PunjabCapitalResearch, #FundamentalsThroughTheNoise
The Licensee's Dilemma | How Coty's Distress Reprices Beauty Licensing
A levered licensee that rents brand equity it does not own becomes a forced seller of its own contracts. The Gucci exit is the template — and the accessible- prestige fragrance map is quietly consolidating around two buyers. Coty's distress is repricing beauty licensing in real time. The mechanism — a levered licensee forced to sell contracts it does not own — is general; the consolidation it feeds, around L'Oréal and Interparfums, is specific and ongoing. Own the equity, not the rental.
#Coty #Kering #LOreal #Interparfums #BeautyLicensing #LuxuryFinancialization #GovernancePremium #Fragrance #Burberry #HugoBoss #Gucci #DistressedCredit #ConsumerEquity #PunjabCapitalResearch #CapitalInsights #FundamentalsThroughTheNoise
Routing the Profit | Tax Havens as Capital Infrastructure & The Irish Case
The tax havens that shape global capital are not the islands of the popular imagination but a small set of respectable, treaty-networked conduit states. This note reads the plumbing on its own terms — and examines what Ireland's version of it earns, and risks.
The purpose of this note is to explain that system on its own terms — as capital-flow infrastructure rather than scandal — and then to examine the jurisdiction at its centre for US corporates: Ireland. We look at why the structure exists, what it actually provides, what it earns the host country, and why the arrangement is more fragile and more contingent on external policy than the headline surpluses suggest.
#TaxHavens, #ConduitOFC, #Ireland, #CorporateTax, #PillarTwo, #GlobalMinimumTax, #ProfitShifting, #BEPS, #CapitalFlows, #FDI, #CountryByCountryReporting, #SovereignRisk, #IrishEconomy, #OECD, #SideBySide, #CapitalInsights, #PunjabCapitalResearch, #FundamentalsThroughTheNoise
The Financed Book | Niche Premiums, Rated Debt & The RIA Consolidation Stack
On Tuesday, EP Wealth Advisors announced the acquisition of Opes Wealth Management, a Menlo Park firm with roughly $900 million in assets and a practice built around Apple and Google employees. It is EP’s fifth deal of 2026.
The forward risk is a compression trade. A buyer universe expanding this fast eventually contracts — mid-market firms are already pairing up defensively to avoid being acquired and to position for scale — and when buyer count falls, acquisition multiples reverse.
A roll-up financed with rated leverage does not experience that reversal symmetrically: the debt is fixed, the multiple is not.
#WealthManagement, #RIA, #PrivateCredit, #Consolidation, #MnA, #EPWealth, #Ares, #WealthStack, #AssetManagement, #CapitalMarkets, #SovereignAllocators, #PunjabCapitalResearch
The Insurance Engine | How Annuity Float Funds Private Credit & Private Equity
Behind the private-credit boom sits a quieter structural shift: the migration of insurance balance sheets into illiquid lending. Annuity float — long-dated, permanent, low-cost — has become the preferred funding base for direct lending, and the managers who run the credit increasingly own the insurer that funds it. This brief sets out the mechanism, why it works, and where it strains.
#InsuranceCapital, #PrivateCredit, #PrivateEquitym #AnnuityFloat, #Apollo, #Athene, #KKR, #GlobalAtlantic, #Blackstone, #AssetBasedFinance, #SpreadRelatedEarnings, #DirectLending, #CapitalInsights, #PunjabCapitalResearch
Hyperscaler Watch | Meta’s Cloud Pivot, the Circular-Financing Default & Power as the Terminal Constraint Across the Hyperscaler Build-Out
The binding constraint moved again. “Renting the Balance Sheet” traced it from chip to balance sheet; this cycle two hyperscalers moved from buying compute to selling it, pushing the scarce factor one turn further — to owned, resalable capacity — while power emerges as the terminal floor beneath all of it.
Meta’s cloud pivot is the headline, but the deeper tell is that the circular-financing architecture we mapped on the Google–Anthropic axis is now the industry default, visible most cleanly on Amazon–Anthropic, and Oracle is the live stress-test of the “weaker sponsor writes the guarantee” question left open.
#PunjabCapitalResearch, #CapitalInsights, #HyperscalerWatch, #Hyperscalers, #AIinfrastructure, #MetaCompute, #Meta, #GoogleCloud, #AWS, #Anthropic, #Oracle, #Microsoft, #Azure, #CircularFinancing, #VendorFinancing, #ComputeShortage, #Neoclouds, #CoreWeave, #DataCenters, #Capex, #PowerConstraint, #FundamentalsThroughTheNoise
Reading the Recruiting Tape | AUM, Revenue Yield, & the Valuation Gap in Wealth Management
Roughly 37% of advisors, controlling about $10.4 trillion—near 40% ofindustry assets—are expected to retire within a decade; the average advisor is about 51, and only some 42% hold a written succession plan as of early 2026.
Continuity has a measurable price: firms without a documented plan trade at an estimated 15% to 25% discount, advisors who move without a credible continuity narrative can shed up to 22% of assets in the transition, and roughly four in five heirs intend to replace an inherited advisor with whom they have no prior relationship.
Against all of that, a multi-year, team-based handoff holds client retention near 95%. A book that arrives with its own successor is not merely larger—it is structurally more durable, and durability is the attribute a premium multiple is paying for.
The channel must give the next generation visible equity and a defined path, or watch its enterprise value decay one retirement at a time.
#WealthManagement , #RIA, #AdvisorRecruiting ,#Valuation , #OrganicGrowth,#RevenueYield ,#SuccessionPlanning ,#Merrill ,#Wealthspire , #PrivateEquity · #TheWealthStack,#CapitalInsights, #PunjabCapitalResearch
The Wealth Stack | The Last Mile to Capital
The final module off The Wealth Stack, and the close of the series. The advice layer is the last mile — the relationship through which capital is actually directed. Read against the obvious narrative, advice is not dying; it is bifurcating, and agentic AI is widening the split rather than collapsing it. This note completes the four-layer read top to bottom, and resolves where, in a stack being commoditised from every direction, durable value finally comes to rest.
#WealthStack, #Advice, #AgenticAI, #RoboAdvisors, #HybridAdvice, #FinancialAdvisors, #RIA, #GreatWealthTransfer, #GenerationalWealth, #FeeCompression, #CostToServe, #WealthTech, #DistributionReset, #ClientRelationships, #SuccessionRisk, #CapitalInsights, #PunjabCapitalResearch, #FundamentalsThroughTheNoise, #Allocators, #FamilyOffices, #SovereignWealth
The Memory Squeeze | Micron Soaring & Apple Raising Prices is the Same Story
AI companies are buying one special kind of memory chip by the truckload to build their data centres. The three firms that make memory — Micron, SK Hynix, Samsung — have pointed their factories at that high-value AI memory and away from the ordinary memory in laptops and phones. Ordinary memory is now scarce, so its price has more than doubled. Micron, which sells the chips, is posting record profits. Apple, which buys them, just raised prices on Macs and iPads. Same shock — opposite ends.
#MemoryCrunch, #RAMageddon, #Micron, #Apple, #AIInfrastructure, #DRAM, #HBM, #Semiconductors, #CapitalInsights
The Coupon on the Reserve | How the Preferred Dividend Made Strategy a Forced Seller
This is the sequel to a question we raised in The Reserve That Sells Itself. There, the argument was that bitcoin fails the test of a reserve asset because its holders are structurally disposed to sell under stress.
A perpetual preferred was supposed to let Strategy hold Bitcoin forever. Its coupon did the opposite — it turned the company's reserve into a funding source, and exposed the contradiction sitting at the center of the entire Bitcoin-treasury model. Here we can name the mechanism. In the treasury-company model, the forced seller is not a behavioural tendency or a failure of conviction. It is a line item on the capital structure: the coupon.
#Bitcoin, #Strategy, #MicroStrategy, #MichaelSaylor, #STRC, #PreferredStock, #mNAV, #TreasuryCompanies, #ReserveAssets, #CapitalStructure, #ForcedSeller, #Convexity, #Reflexivity, #Metaplanet, #CryptoMarkets, #PunjabCapitalResearch, #CapitalInsights, #FundamentalsThroughTheNoise
Polymarket’s Staged Wins & The Venue Premium
How a fabricated-virality disclosure reprices integrity risk across the prediction-market complex
A Wall Street Journal investigation finds that none of roughly $1.9m in bets shown across 1,105 promotional videos were real. Stripped of the marketing-scandal framing, this is a venue-integrity event — and it lands precisely as the regulated rail pulls decisively ahead of the offshore one. The next phase of the prediction-market race will not turn on whether creators can make the odds go viral. It will turn on which venue can show that the book underneath is cleaner than the campaign that sold it.
#PredictionMarkets, #Polymarket, #Kalshi, #MarketIntegrity, #CFTC, #VenueRisk, #RegulatoryArbitrage, #EventContracts, #DataIntegrity, #CapitalMarkets, #FundamentalsThroughTheNoise, #PunjabCapitalResearch
The Perpetual Wrapper | Always On Leverage is Becoming the Default Venue for Global Price Discovery
Perpetual futures began as a crypto-native workaround to avoid contract rollover. In the space of roughly nine months they have crossed three thresholds at once — in the assets they wrap, the venues that list them, and the jurisdictions that police them. The product is no longer a sidecar to spot crypto; it is becoming the always-on layer where price is discovered first and the cash market reacts second.
The standing question. If the perpetual becomes the venue where global macro price is discovered first — across the weekend gap, across asset classes, across jurisdictions — then the value of the dated-futures complex and the exchange oligopoly that owns it is being quietly repriced. The equity market has already started. CME’s lawsuit is what it looks like when an incumbent recognises that the moat is the thing being competed away.
#PerpetualFutures, #Perps, #MarketStructure, #PriceDiscovery, #RWA, #Tokenisation, #Hyperliquid, #Kalshi, #CFTC, #CME, #DoddFrank, #FundingRate, #AutoLiquidation, #Leverage, #DerivativesMarkets, #CryptoDerivatives, #VenueIntegrity, #Macro, #CapitalInsights, #PunjabCapitalResearch, #FundamentalsThroughTheNoise
Private Equity's Accounting Wave | The Consolidation Story & Its Financing
Private equity has spent four years buying its way into the accounting profession. In a single fortnight in June, two more of the largest US firms outside the Big Four agreed to sell: Crowe to KKR in a deal valuing it near $3 billion, and Eide Bailly to Reverence Capital at about $1.8 billion. Both are reported as equity stories — a sponsor takes majority control, partners monetise, the firm gets capital for technology and acquisitions. That framing is correct but incomplete. The mechanism that lets the wave continue, and the channel that ultimately funds it, sit one layer below the headline. This note maps both: why the profession is being consolidated, and how the consolidation is paid for.
#PrivateEquity, #PrivateCredit, #AccountingRollup, #Crowe, #KKR, #EideBailly, #ReverenceCapital, #InsuranceCapital ,#GlobalAtlantic, #Athene, #DirectLending, #AlternativePracticeStructure, #ProfessionalServices, #RepricingCognitiveLabor, #CapitalInsights, #PunjabCapitalResearch
The Unicorn Repricing | Stale Marks, the Liquidity Veto, & the Allocator's Private-Market Reckoning
The Unicorn Repricing | Stale Marks, the Liquidity Veto, & the Allocator's Private-Market Reckoning
A Stanford database now counts hundreds of “zombie” unicorns. The headcount is the symptom. The story underneath it is a private-market repricing that allocators have spent two years carrying at par.
The Economist this week gave a name to something LPs have felt in their net asset values for two years: the zombie unicorn — a company once marked above $1bn, now a shadow of that figure.The zombie count is a lagging indicator. The leading indicator is what private marks will look like once the 2021 vintage is forced to transact. The undead are not a curiosity at the edge of the portfolio — they are a preview of the repricing the whole private book has been deferring.
#PrivateMarkets, #VentureCapital, #Unicorns, #Repricing, #Liquidity, #NAV, #SecondaryMarket, #ContinuationFunds, #AllocatorStrategy, #AICapital, #Pitchbook, #SovereignWealth, #FamilyOffice, #PunjabCapitalResearch, #CapitalInsights, #FundamentalsThroughTheNoise
Micron's Record Print, Read Twice | The Contract Wall and the China Memory Split
One blowout quarter, two structural reads. Micron is converting a shortage into contracted revenue; China is converting the same scarcity into market share, IPO capital, and capacity. The print validates the supercycle, but the durable signal is the conversion of scarcity into position — contractual on Micron's side, structural on China's. Neither wrapper repeals cyclicality; both raise the normalized base around which the next cycle oscillates.
#Micron, #MemoryChips, #DRAM, #NAND, #HBM, #Semiconductors, #AIInfrastructure, #MemorySupercycle, #SupplyAgreements, #ContractedRevenue, #Anthropic, #CircularFinancing, #CXMT, #YMTC, #ChinaTech, #SelfContainment, #MultipolarOrder, #FaultLines, #CapitalInsights, #PunjabCapitalResearch, #FundamentalsThroughTheNoise
The Wealth Stack | The Wrapper Decides - How Packaging sets the Threshold of Access
In The Wealth Stack we named four layers between an asset manager and the capital it manages, and called the second of them packaging: the wrapper that carries a strategy to an investor. In the spine we made a claim about this layer that is easy to pass over and worth slowing down on — that the wrapper is where democratisation actually happens. Not the manager deciding to be generous. Not the regulator deciding to permit. The wrapper. It sets the minimum cheque, the liquidity terms, the tax treatment and the eligibility threshold, and those four things together decide who is allowed to own the asset at all.
The second module off The Wealth Stack. The packaging layer is where democratisation actually happens — the wrapper, not the manager's intent or the regulation alone, decides who is allowed to own an asset. This note ranks the wrappers by how far down the wealth tiers each one pushes access, then reads the newest and most over-narrated of them — the token — precisely.
#WealthStack, #Packaging, #Wrappers, #ETF, #DirectIndexing, #SMA, #EvergreenFunds, #IntervalFunds, #SemiLiquid, #PrivateMarkets, #PrivateCredit, #Tokenisation, #RWA, #RetailThreshold, #BUIDL, #LiquidityMismatch, #TargetDateFunds, #CapitalInsights, #PunjabCapitalResearch, #FundamentalsThroughTheNoise, #Allocators, #FamilyOffices, #SovereignWealth
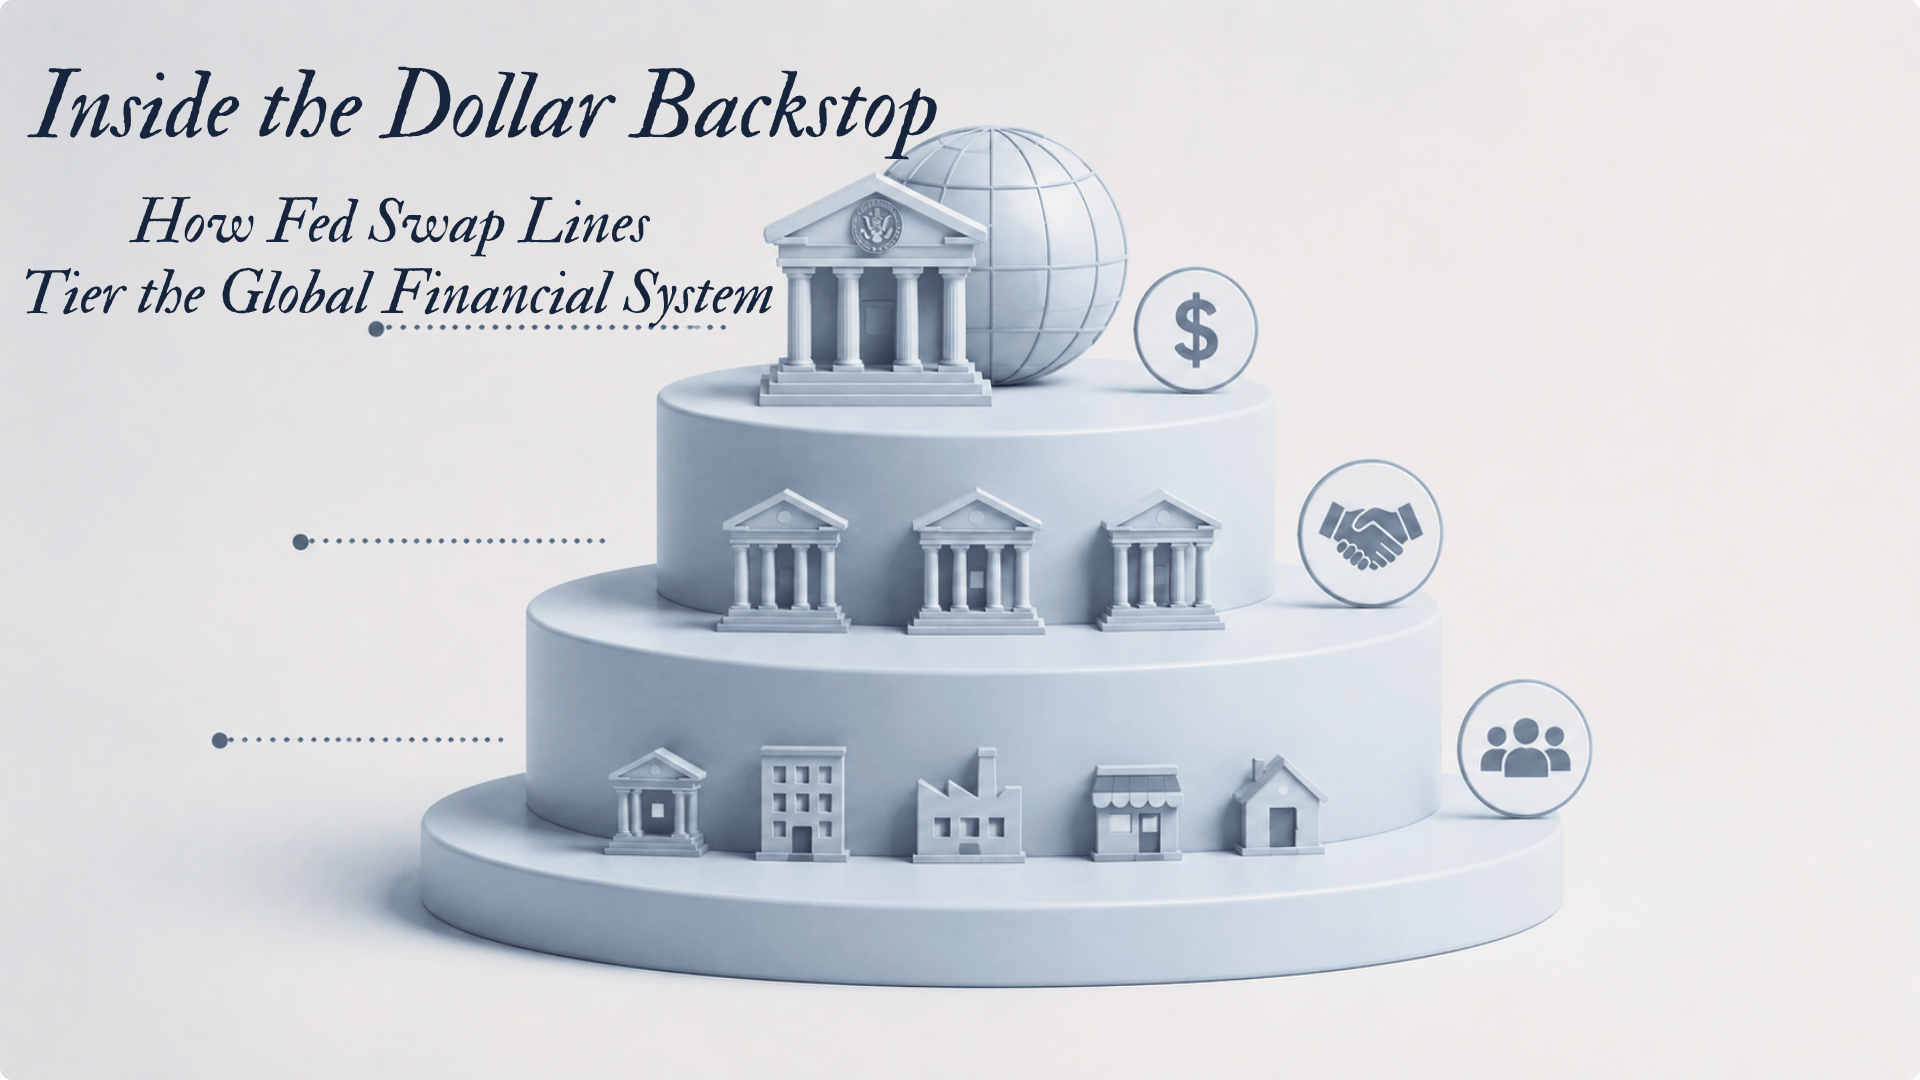
Inside the Dollar Backstop | How Fed Swap Lines Tier the Global Financial System
A central-bank swap line is not one facility but a hierarchy of dollar access. Where a sovereign sits in that hierarchy has quietly become a read on alliance, integration, and funding resilience — which is why reserve-rich states are now queuing to get in.
#DollarLiquidity, #FedSwapLines, #FIMARepo, #ReserveCurrency, #DollarBackstop, #UAE, #GulfFinance, #Petrodollar, #Dedollarization, #SovereignRisk, #CentralBanks, #FinancialStatecraft, #CurrencyPeg, #CapitalInsights, #PunjabCapitalResearch, #FundamentalsThroughTheNoise
The Japanese Carry Trade | Why Japan’s Hike to 1% Erodes the Funding but Hasn’t Flipped the Flow
The Japanese Carry Trade | The Margin, Not the Direction Two Carry Trades, & Why Japan’s Hike to 1% Erodes the Funding but Hasn’t Flipped the Flow
The Japanese Carry Trade | The Margin, Not the Direction Two Carry Trades, & Why Japan’s Hike to 1% Erodes the Funding but Hasn’t Flipped the Flow On 16 June the Bank of Japan lifted its policy rate to 1.00%, the highest since 1995. The tape reached for “the great unwind.” Yet USD/JPY sits near 160 and Tokyo has spent ~¥11.7tn defending the yen since late April. The trade has not snapped. What is breaking is quieter, and harder to reverse.
Fundamentals through the noise The noise is “the great unwind” — a single, cinematic event endlessly re-forecast off the August-2024 template. The fundamental is two trades on two clocks: a speculative leg that is lighter and less dangerous than the tape implies, and a real-money leg that is repricing quietly and will not reverse on a press conference. Japan at 1.00% has changed the margin of the world’s most important funding trade without yet changing its direction. The direction will change — not in a session, but in the patient redeployment of a generation’s savings now that yield, at last, is real at home.
#YenCarryTrade, #BankOfJapan, #BOJ, #USDJPY, #JGB, #MonetaryNormalization, #Repatriation, #CrossCurrencyBasis, #HedgedYield, #TermPremium, #FXStrategy, #Macro, #CrossAsset, #AssetAllocation, #SovereignWealth, #FamilyOffice, #PunjabCapitalResearch, #FundamentalsThroughTheNoise
The Wealth Stack | How the Distribution Layer is being Remade
The Wealth Stack | The Rail & the Vault - How the Distribution Layer is being Remade
In The Wealth Stack Intro video, we placed four layers between an asset manager and the capital it manages: manufacturing, packaging, distribution, advice. We called distribution the contested layer — the channel that owns the rail to the investor's money, and the place where control of capital physically resides. This module is that layer made live.
#WealthStack, #DistributionReset, #RIA, #Wirehouse, #BreakawayAdvisors, #RIAConsolidation, #401k, #AlternativeInvestments, #PrivateMarkets, #PrivateEquity, #PrivateCredit, #TargetDateFunds, #ERISA, #DOL, #AndersonVIntel, #RetirementAssets, #CapitalInsights, #PunjabCapitalResearch, #FundamentalsThroughTheNoise, #Allocators, #FamilyOffices, #SovereignWealth
What Buffett’s Apple Exit & Berkshire’s Alphabet Bet Reveal About Valuation Discipline
Price, Not Prophecy | What Buffett’s Apple Exit & Berkshire’s Alphabet Bet Reveal About Valuation Discipline
It is easy to turn Buffett into a mystic who simply sees further than everyone else. The Apple and Alphabet story suggests something less magical and far more usable. He did not need to know that memory costs would spike, or that Google’s search business would prove more durable than the doubters feared. He needed only to keep asking one question: is the price I am being offered higher or lower than what this business is worth?
That is the quiet power of valuation discipline. It does not ask you to be right about the future, which is impossible. It asks you to be honest about the present, which is merely hard. In a market once again paying dearly for a future in which everything goes right, that is a distinction worth keeping close.
#ValuationDiscipline, #WarrenBuffett, #BerkshireHathaway, #Apple, #Alphabet, #Google, #GregAbel, #MarginOfSafety, #ValueInvesting, #CapitalAllocation, #TechValuations, #MagnificentSeven, #AIBubble, #PriceVsValue, #PunjabCapitalResearch, #CapitalInsights, #FundamentalsThroughTheNoise