Global Bond Market | The Issuer as Buyer
In a single early‐September session the US ten‐year touched 4.81% (a near three‐year high) with the thirty‐year back near a nineteen‐year peak; British yields hit their highest since 2008, Australian ten‐years a fifteen‐year high, German bund futures their weakest since 2011, and French OAT futures a record low.
August’s buyback — at least $4bn across ten‐ to thirty‐year bonds — was the yen‐era curve defense pointed inward, and it was overrun within weeks, the thirty‐year back near its high. The revived bond‐vigilante base case is the tell: bills funding repeat buybacks should the ten‐year reach 5% — a curve managed against its own gravity, with the issuer paying first in its own credibility.
#Treasuries, #SovereignDebt, #BondVigilantes, #Buybacks, #AICapex, #SafeHaven, #SixtyForty, #Gold, #ReserveFragmentation, #FinancialRepression, #JGBs, #MacroStrategy
Fault Lines | The Multipolar Order | The Custody Layer & Hong Kong’s Gold Hub
Hong Kong’s fourth attempt to become a gold hub is being read through the wrong lens. Most commentary measures it against London and New York on price and liquidity—and on that scorecard it looks like another underpowered venue. But the venue is not the point. What is being assembled in Hong Kong is a settlement and custody layer for physical gold that sits outside Western jurisdiction, in the Asian time zone, and increasingly on a yuan rail.
That is a reserve-fragmentation story, not a trading story—and it is closer to working than the “fourth try” framing admits. The objective is not to mint a “Hong Kong price” or to unseat London and New York on discovery. The goal is optionality of custody: a trusted, Asian-time-zone venue to trade, store, clear and deliver physical gold outside Western jurisdiction, with a yuan rail attached.
#Gold, #ReserveFragmentation, #HongKong, #Dedollarisation, #RMBInternationalisation, #MultipolarOrder, #CentralBanks, #Custody, #FaultLines
The Gold Stack | The 2020–2026 Repricing & Access Layers from Central Bank Vaults to Retail Wallets
Gold near US$4,400 is not one market. It is a sovereign floor and a Western margin trad‐ ing under the same ticker — and the repricing that carried it here ran from the top of the ownership stack down. Trace the move, map the stack, and the same picture answers two questions at once: why gold rose, and how anyone from a central bank to a retail saver actually holds it.
#Gold, #GoldStack, #CentralBankGold, #ReserveFragmentation, #Dedollarization, #PreciousMetals, #GoldETFs, #TokenizedGold, #RoyaltyStreaming, #AllocatorsRead, #FundamentalsThroughTheNoise
Closing the Retail Gold Leverage Channel | China's Precious Metals Cleanup, Hong Kong Gold Build, & Reallocation of Participation Rights
On 24 June, ICBC gave notice that from the end-of-day settlement on Friday 24 July 2026 it would cease its agency business for individual precious metals auction trading on the Shanghai Gold Ex‐ change. The named contracts —are the full retail spot and deferred complex in both metals. China Construc‐ tion Bank announced the same date a day later; Ping An, China Guangfa and Postal Savings Bank had already exited. Holders were told to close out or take delivery before the deadline.
Today's deadline is a market-structure event, not a demand event, and says nothing about the direc‐ tion of gold. The more interesting question opens today: whether a domestic market with retail lever‐ age removed and an offshore clearing venue about to go live converge into a credible pricing mechan‐ ism — settled by whether foreign institutions and central banks actually clear through Hong Kong.
#China, #PreciousMetals, #Gold, #Silver, #ShanghaiGoldExchange, #HongKong, #MarketStructure, #RetailLeverage, #BankRegulation, #RMBInternationalisation, #CentralBankGold, #CapitalInsights, #PunjabCapitalResearch
The Denial & the Drawdown | How India's Reserve Opacity Became a Policy Instrument
The June dispute over whether the RBI sold $12 billion of gold was never resolvable — and that is the point. India has acquired a reserve-management doctrine in which denial and drawdown coexist inside the reporting calendar, and an intervention posture that makes the ambiguity useful. For allocators, the question was never whether the sale happened. It is that a structural accumulator's bullion is now contingent FX liquidity — and its disclosure seam is now a policy instrument.
Step back from India and the episode reads as a data point in a broader migration. Gold's share of the reserve stack has climbed as central banks treat it as a hedge against dollar and geopolitical risk.
#FaultLines, #ReserveFragmentation, #RBI #Rupee, #Gold, #Dedollarisation, #ForexReserves, #CentralBanks, #EMcurrencies, #MultipolarOrder, #PunjabCapitalResearch, #FundamentalsThroughTheNoise
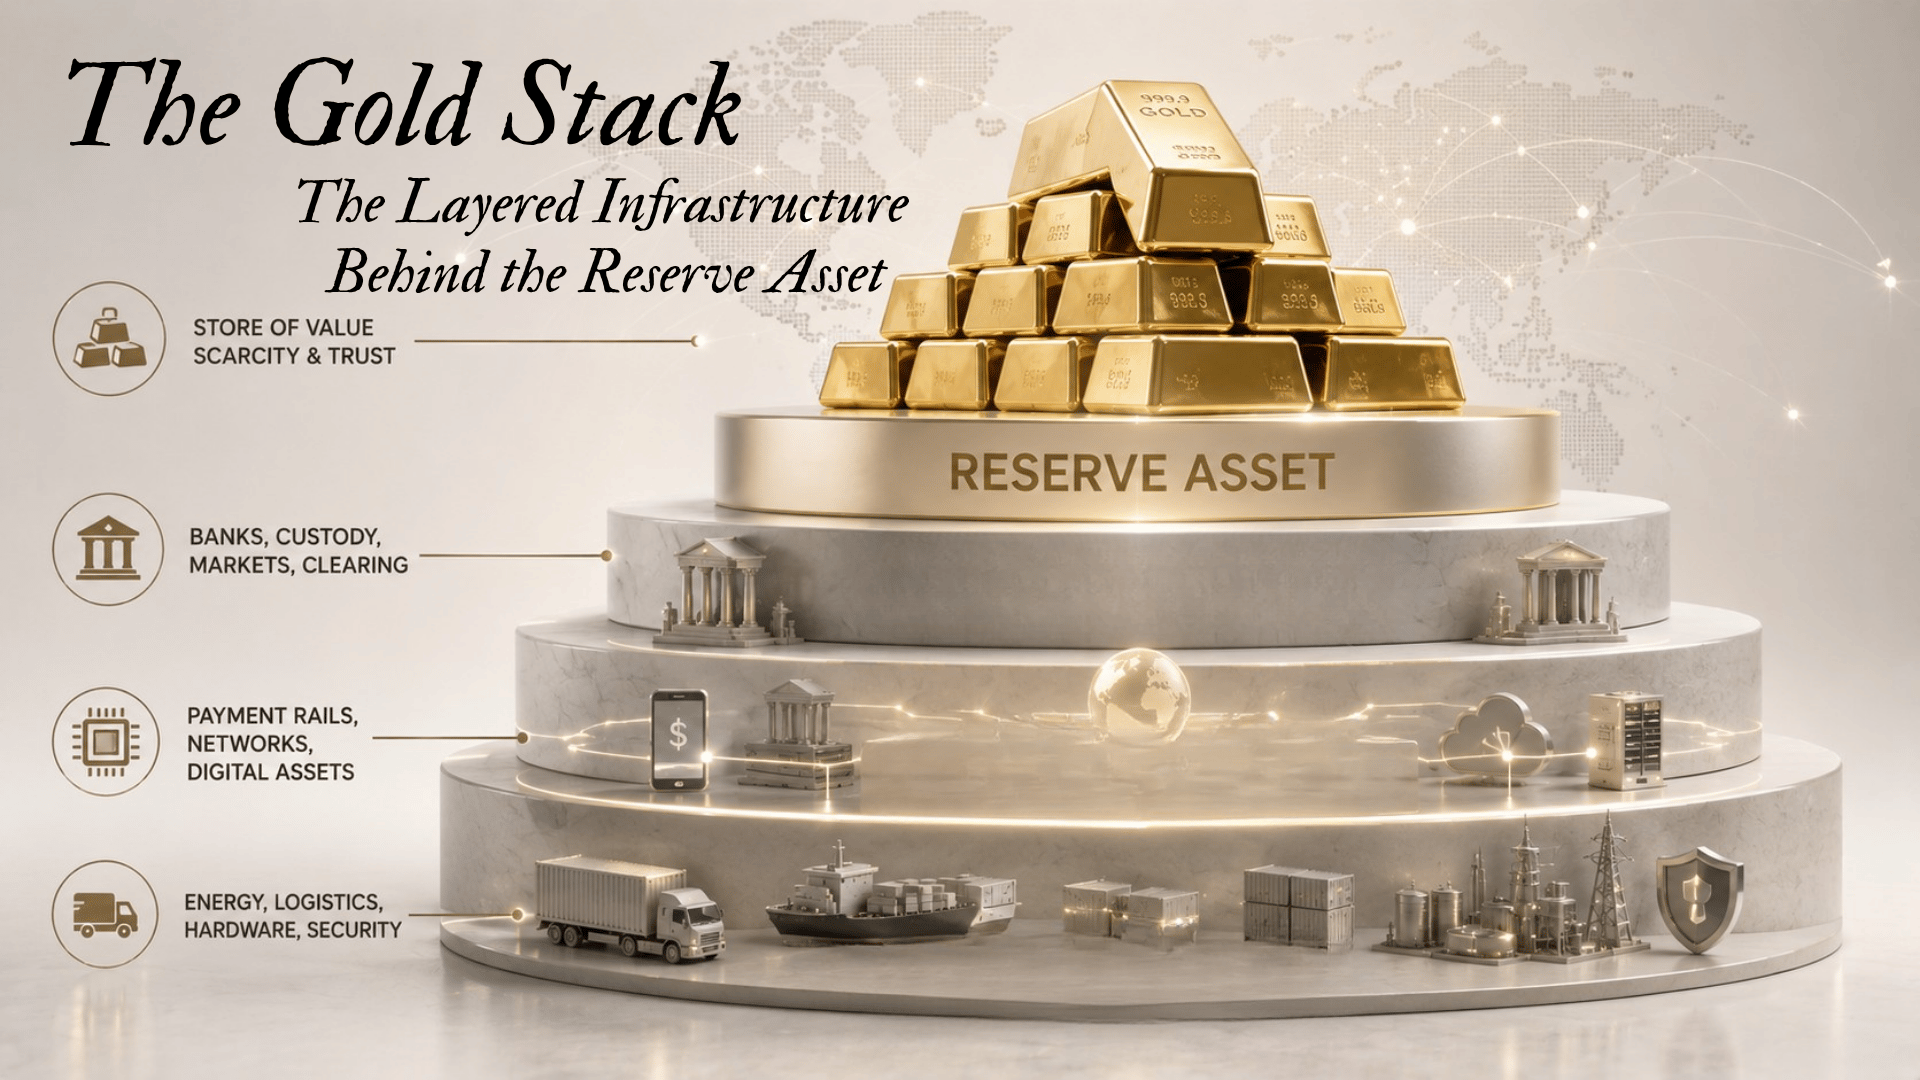
The Gold Stack | The Layered Infrastructure Behind the Reserve Asset
Gold’s monetary role is deepening faster than the market architecture that carries it. This note sets that noise aside and maps the architecture itself — as a stack of distinct functional layers rather than a single network — and argues that the layers are now separating along seams set by what binds each one in place. No view is taken on which centre prevails; the object is the map.
#Gold, #ReserveAssets, #MarketStructure, #CentralBanks, #Bullion, #Custody, #PriceDiscovery, #Refining, #Clearing, #GoldStack, #Delamination, #CapitalInsights, #PunjabCapitalResearch, #FundamentalsThroughTheNoise, #Macro, #Allocators